Global EV Fleet Displaces Fivefold More Oil Than Five Years Ago
Battery electric vehicles now represent 25 percent of new car sales worldwide, displacing 1.2 million barrels of crude oil daily since the Glasgow summit.
EXECUTIVE BRIEF // KEY TAKEAWAYS
Battery electric vehicles now represent 25 percent of new car sales worldwide, displacing 1.2 million barrels of crude oil daily since the Glasgow summit.
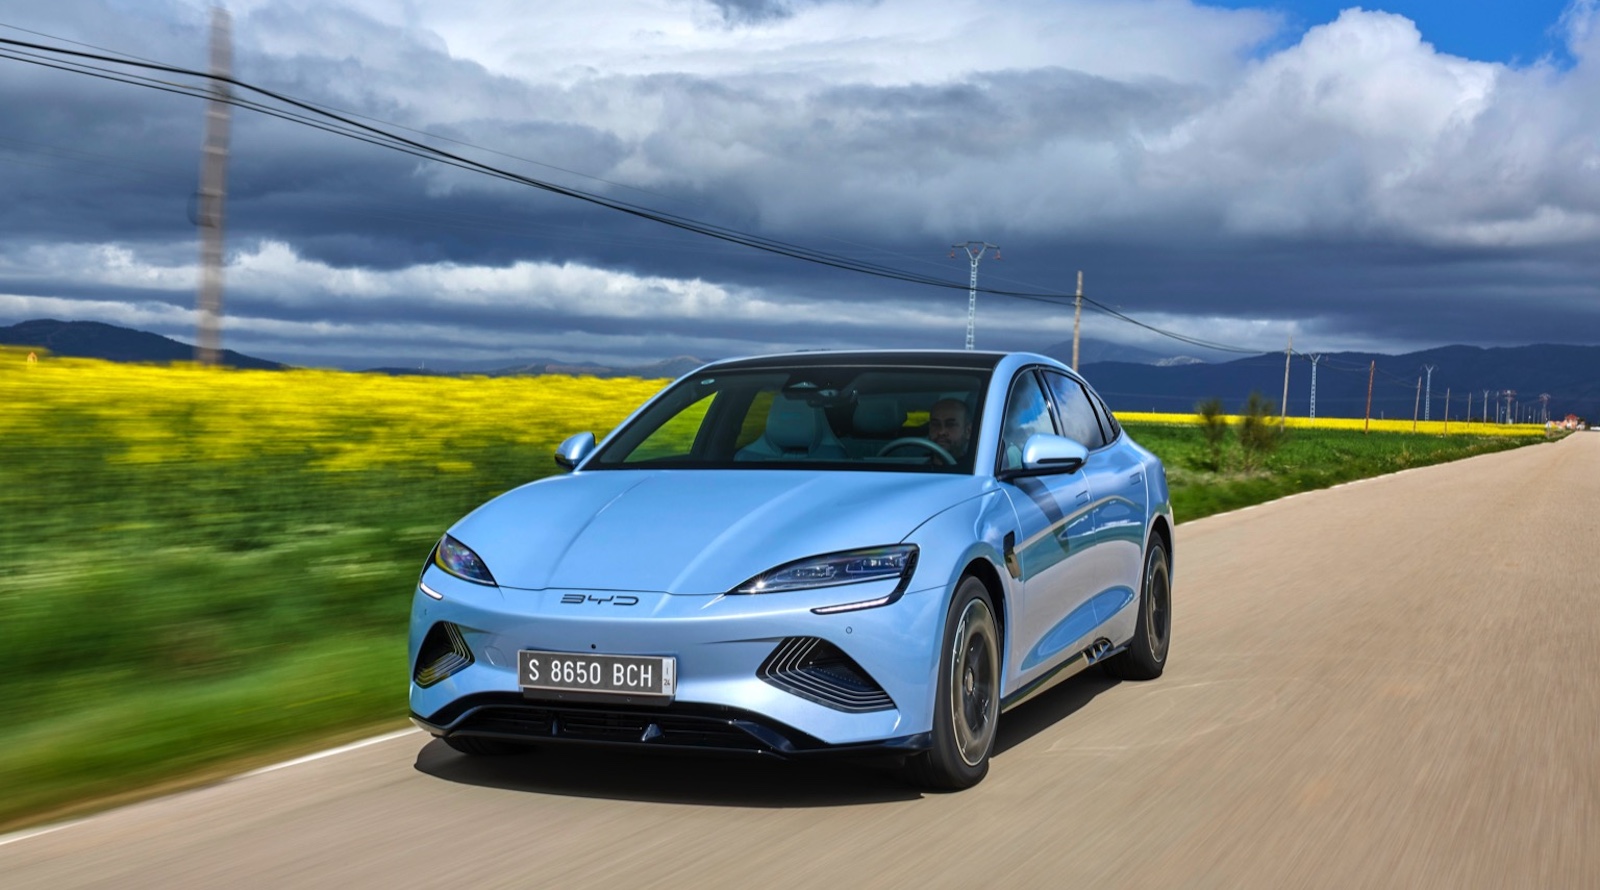
Battery electric vehicles now displace five times more global oil consumption than they did five years ago, removing approximately 1.2 million barrels of crude oil demand per day, according to a new analysis reported by CleanTechnica and Transport & Environment (T&E). Five years after the landmark climate commitments established at the Glasgow summit, battery electric vehicles (BEVs) have emerged as the single most effective mechanism for curbing structural petroleum demand across the global transportation sector. While fully electric passenger cars currently represent roughly 4.2 percent of the total global vehicle fleet on the road, they now account for a full quarter of all new passenger car purchases worldwide.
The rapid divergence between fleet share and new sales velocity signals a critical inflection point for international energy markets, automotive original equipment manufacturers, and refining infrastructure investors. Even when cumulative fleet turnover lags behind annual showroom adoption, the compounding daily displacement of 1.2 million barrels of oil demonstrates that electrification is moving from a regulatory compliance exercise into a primary determinant of global liquid fuel demand trajectories.
Five Years Since Glasgow: From Policy Pledges to Fleet Reality
The analytical assessment compiled by Transport & Environment and highlighted by CleanTechnica evaluates the tangible progress of road transport decarbonization over the five-year interval following the Glasgow climate accords. At the time of the Glasgow summit, electric mobility remained heavily concentrated in a handful of early-adopter jurisdictions supported by direct fiscal subsidies. In the intervening five years, battery pack cost reductions, expanded charging corridors, and tighter fleet-wide emissions standards have transformed BEVs into a mainstream industrial category.
According to T&E, electric vehicles have proven to be the single most effective policy and technological lever to actively reduce oil consumption. Unlike incremental fuel-efficiency mandates for internal combustion engine vehicles—which have historically suffered from rebound effects and a consumer shift toward heavier sport utility vehicles—direct battery electrification permanently removes tailpipe petroleum demand from every vehicle placed into service. Although a 4.2 percent share of the active global car fleet appears modest in isolation, the fivefold expansion in daily oil displacement illustrates how high-utilization newer vehicles disproportionately affect immediate fuel consumption.
Quantifying the 1.2 Million Barrel Daily Displacement
From an operational and macroeconomic perspective, the displacement of 1.2 million barrels of oil per day represents a substantial structural shift in energy balances. For global petroleum refiners and fuel distributors, road passenger transport has historically served as the highest-margin anchor for gasoline and diesel output. Having one in four new vehicles sold worldwide bypass the petroleum supply chain entirely alters long-term capital allocation models for both upstream exploration and downstream refining capacity.
The mechanics behind this fivefold surge rest on the arithmetic of fleet renewal. New vehicles typically log higher annual mileage than older vehicles near the end of their operational lifespan. Consequently, as BEVs capture 25 percent of global new vehicle registrations, their real-world fuel displacement outpaces their 4.2 percent static share of total registered automobiles. Every annual cohort of new electric vehicles layers onto the existing base, creating a cumulative compounding effect that steadily erodes baseline motor fuel demand across major automotive markets in Asia, Europe, and North America.
Strategic Outlook for Automakers and Energy Markets
Looking ahead, the gap between the 4.2 percent total fleet penetration and the 25 percent new-sales capture rate underscores the vast scale of industrial transition already locked into the global automotive pipeline. Even if new EV sales shares were to plateau near current levels, the natural scrappage of aging internal combustion vehicles over the coming decade guarantees that the active BEV fleet share—and its corresponding oil displacement—will continue to climb steeply.
For legacy automakers, battery supply chain operators, and power grid planners, the findings reported by CleanTechnica and T&E reinforce that transport electrification is delivering measurable, large-scale fossil fuel substitution. Industry stakeholders must now navigate the next phase of deployment: scaling regional grid distribution capacity, securing raw material refining, and achieving cost parity in mass-market vehicle segments to sustain momentum beyond the initial quarter of global new car buyers.